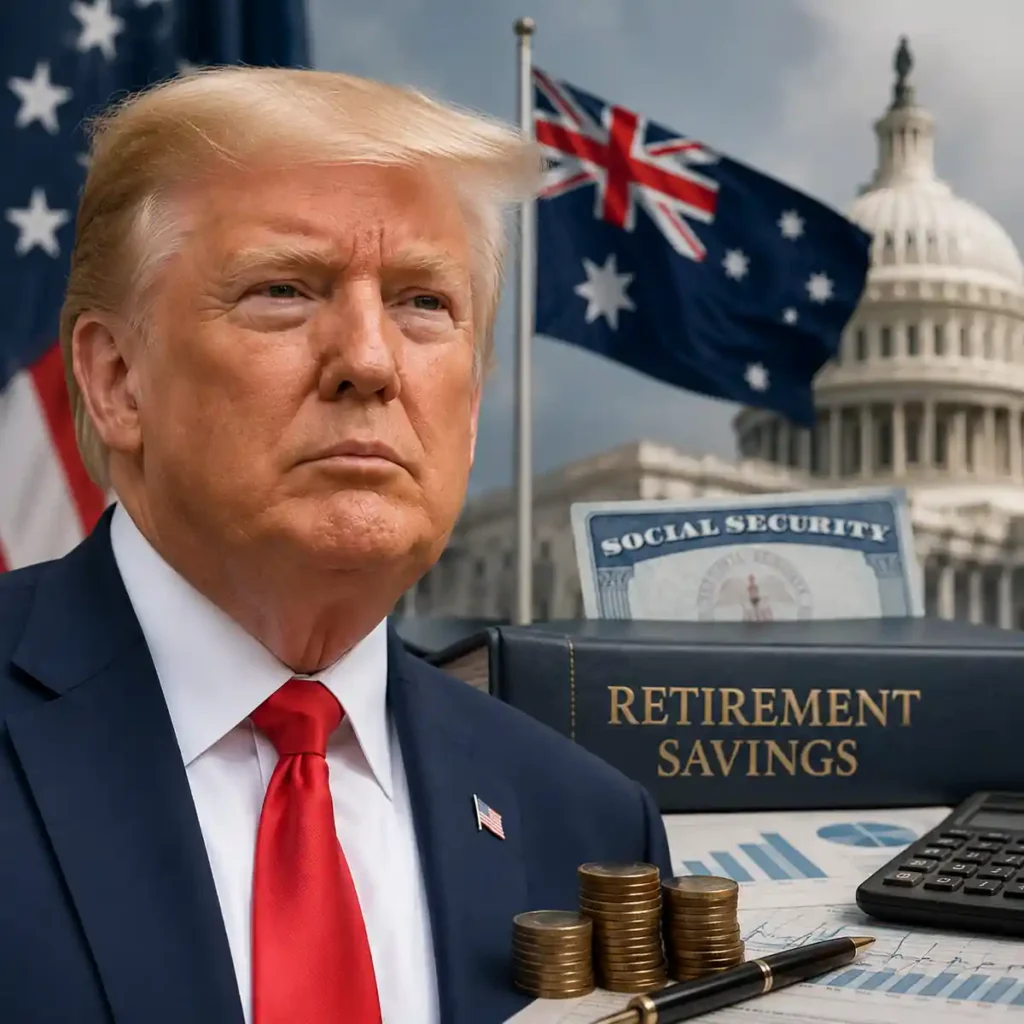

President Donald Trump is looking seriously at Australia’s compulsory retirement-saving system as the United States confronts a looming Social Security funding shortfall and a persistent gap in workplace retirement coverage.
Trump has praised Australia’s approach and said his administration wants to discuss with Congress whether elements could work in America. Australia generally requires employers to contribute 12% of eligible workers’ qualifying earnings into retirement accounts, creating savings that can grow throughout a worker’s career.
For Americans worried about immediate changes, however, the key point is clear: Trump has not announced a plan to replace Social Security, eliminate 401(k)s or impose Australia’s 12% contribution requirement in the United States.
How Australia’s 12% retirement system works
Australia’s compulsory retirement program is known as superannuation, or “super.” Employers generally contribute 12% of eligible employees’ ordinary time earnings into super funds, where the money is invested for retirement.
From July 1, 2026, Australia’s Payday Super rules generally require employers to make super contributions alongside regular pay cycles, with contributions typically needing to reach the employee’s fund within seven business days.
Australia also operates an Age Pension. Unlike U.S. Social Security, it is subject to income and asset tests and is designed to provide support to eligible older Australians who need it.
Workers wanting to understand the Australian side of the debate can also look at how superannuation funds invest retirement savings, since compulsory contributions ultimately become investment assets held for workers.
Why Trump is interested in the Australian model
Australia’s system receives stronger international marks than the U.S. system. The 2025 Mercer CFA Institute Global Pension Index gave Australia a B+, compared with a C+ for the United States.
A major attraction is coverage. While many Americans have 401(k)s or similar workplace plans, millions do not participate in one. Australia’s compulsory approach makes retirement saving much harder to avoid or postpone.
What could happen to Social Security?
Trump’s interest comes as Social Security approaches a significant financing deadline. According to the Social Security Administration’s 2026 Trustees projections, the Old-Age and Survivors Insurance Trust Fund is expected to deplete its reserves during 2032 without congressional action.
After depletion, continuing program income is projected to cover about 78% of scheduled OASI benefits. That does not mean Social Security disappears. Payroll-tax revenue would continue flowing into the program, but it would not be enough to pay 100% of scheduled benefits.
The size of Social Security payments already varies significantly depending on claiming age and earnings history, as illustrated by average Social Security benefits by age in 2026.
Could Australia’s system replace Social Security?
No replacement has been announced. Such a transition would also be extremely complicated.
Current workers have paid Social Security taxes while expecting future benefits, and current retirees already depend on those payments. Introducing mandatory individual accounts would not erase those existing obligations.
Some retirement-policy experts instead argue that broader private saving could eventually allow Social Security to focus more heavily on lower earners. Separate proposals have suggested limiting very high Social Security benefits to improve the program’s finances, but those ideas are not an announced Trump policy.
Could Americans be required to save 12%?
There is currently no U.S. 12% retirement mandate. Australia’s figure describes its existing employer Super Guarantee, not a contribution rate Trump has proposed for American workers.
A U.S. mandate would raise difficult questions. Congress would have to decide whether employers or workers contribute, whether participation is compulsory, how existing 401(k)s are treated and how a new system interacts with Social Security payroll taxes.
Critics also argue that mandatory employer contributions could eventually affect wages or other compensation, while supporters say compulsory saving would prevent more workers from reaching retirement with little money outside Social Security.
State Farm $5 Billion Payout: Who Qualifies and What Customers Need to Know
Social Security Full Retirement Age 2026: What Retirees Need to Know
What happens to 401(k)s and IRAs?
There is no announced plan to abolish 401(k)s. The administration is actually pursuing another initiative intended to expand access to individual retirement accounts.
Trump signed an executive order directing the Treasury Department to establish TrumpIRA.gov by January 1, 2027. The platform is aimed particularly at independent contractors, self-employed people, part-time workers and others without employer-sponsored retirement plans.
Another important change is the federal Saver’s Match, created under the SECURE 2.0 Act. Eligible lower- and moderate-income savers can receive a federal matching contribution worth as much as $1,000 per person for qualifying retirement savings.
What Americans should watch now
Current retirees do not need to change their Social Security arrangements because of Trump’s comments, and workers do not need to move existing 401(k) savings. No Australian-style federal mandate has taken effect.
The next major signal will be whether the White House and Congress develop a detailed proposal specifying contribution rates, employer obligations and how new retirement accounts would interact with Social Security and existing 401(k)s.
For now, Australia represents a model Trump wants Washington to study rather than a new American retirement system. The bigger question is whether that interest eventually becomes legislation as Congress faces the increasingly urgent task of strengthening Social Security while helping more Americans build retirement savings of their own.

Make Swikblog your go-to source on Google for reliable updates, smart insights, and daily trends.